How to Finance a Home Renovation Project: 6 Smart Options
Compare cash-out refinance, HELOC, personal loans, and FHA 203(k) to finance your renovation. Call (833)-700-4293 for contractor quotes and expert help.
By Julia Dawson
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
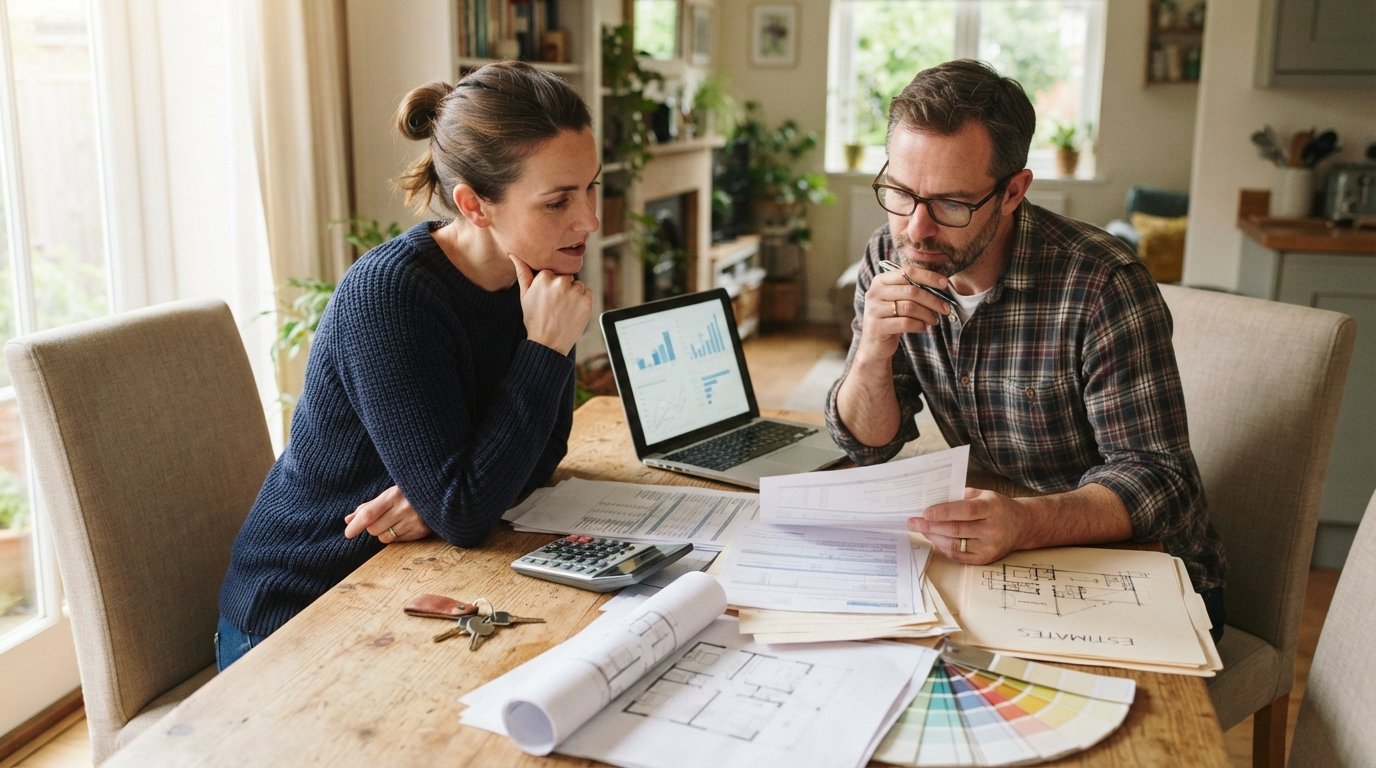
You have big plans for your home: a new kitchen, a primary suite addition, or maybe a full basement finish. Then you see the estimates, and the number is higher than your savings account can cover. You are not alone. Most homeowners cannot pay for a major renovation in cash, and that is perfectly normal. The real challenge is not just finding money; it is choosing the right financing method so you do not drown in high interest or get stuck with a loan that does not fit your project timeline.
How to finance a home renovation project depends on three key factors: how much equity you have, how long the project will take, and how much risk you can tolerate. A cash-out refinance might offer the lowest rate but resets your entire mortgage. A personal loan is fast and unsecured but comes with higher interest. Government-backed renovation loans like FHA 203(k) or Fannie Mae HomeStyle let you wrap the renovation cost into your mortgage, but they require strict paperwork and approved contractors. This guide walks you through each option, explains how lenders handle contractor payments, and warns you about common pitfalls so you can move forward with confidence.
Cash-Out Refinance vs. HELOC vs. Personal Loan: Rate and Risk Comparison
When you need a lump sum for a renovation, three mainstream options dominate the conversation: cash-out refinance, home equity line of credit (HELOC), and personal loan. Each has a different cost structure and risk profile. A cash-out refinance replaces your existing mortgage with a larger one and gives you the difference in cash. Because it is secured by your home, rates are typically the lowest among these three, often close to standard mortgage rates. However, you pay closing costs (2% to 5% of the loan amount), and you reset your mortgage term, which could mean paying interest for many more years. It works best if you already planned to refinance and your current rate is not significantly lower than market rates.
A HELOC is a second mortgage that works like a credit card: you draw funds as needed up to a limit, and you pay interest only on what you borrow. HELOCs usually have variable rates, which means your payment can rise if the prime rate increases. They are ideal for projects with uncertain costs or phased timelines because you can draw money in stages. But remember that a HELOC is still secured by your home; if you default, you risk foreclosure. Personal loans are unsecured, so they do not put your house on the line. Rates are higher (often 6% to 15% or more depending on credit), but approval can be fast, and the loan amount is fixed. Personal loans are best for smaller projects (under $50,000) where you want simplicity and no home equity requirement.
Here is a quick comparison to help you weigh the trade-offs:
- Cash-out refinance: Lowest rate; closing costs; resets mortgage term; best if you refinance for other reasons too.
- HELOC: Variable rate; draw as needed; no closing costs in many cases; risk of payment increase; best for phased projects.
- Personal loan: Fixed rate; unsecured; fast approval; higher interest; best for smaller, short-term projects.
Before you choose, get quotes from multiple lenders. Even a 1% difference in rate can add thousands in interest over the life of the loan. Also consider how long you plan to stay in the home; if you move within a few years, a cash-out refinance may not recoup its closing costs. And if you are financing energy-efficient upgrades like solar panels, check out how solar panels increase home value and reduce bills to see if the long-term savings offset the financing cost.
How Lenders Handle Contractor Draws and Lien Waivers
When you finance a renovation, especially with a loan secured by your home, lenders do not simply hand you a check for the full amount. They want to ensure the work gets done and that subcontractors and suppliers get paid. That is where the draw system and lien waivers come in. A draw is a scheduled disbursement of funds released as portions of the project are completed. For example, your lender might release 30% at the start, 30% after rough framing, 30% after fixtures are installed, and the final 10% after a final inspection. This protects you because you do not pay for work that has not been done, and it protects the lender because the home remains valuable collateral.
Lien waivers are documents signed by contractors and subcontractors confirming they have been paid for work performed up to a certain date. Without a lien waiver, a subcontractor could file a mechanic's lien against your property if the general contractor fails to pay them, even if you already paid the general contractor. Lenders typically require lien waivers before releasing each draw. As a homeowner, you should also request lien waivers directly from major subcontractors. This step adds paperwork, but it prevents nasty surprises like a lien on your home after the project is finished.
If you use a personal loan or a credit card, you have more freedom because the lender does not monitor draws. But that also means you bear the full risk of contractor non-performance. For any project where you are not paying in full upfront, insist on a written draw schedule in your contract and keep records of every payment. A reputable contractor will not hesitate to provide lien waivers and sign a detailed payment schedule.
FHA 203(k) and Fannie Mae HomeStyle Loans for Major Renovations
If your renovation is extensive (think structural changes, full kitchen gut, or adding a bedroom) and you do not have enough equity for a cash-out refinance or HELOC, government-backed renovation loans may be your best bet. The FHA 203(k) loan allows you to purchase or refinance a home and include the cost of renovations in a single mortgage. There are two versions: the Standard 203(k) for major structural work (minimum $5,000) and the Limited 203(k) for minor upgrades (up to $35,000). The appeal is a low down payment (3.5%) and competitive rates. The catch: you must use an FHA-approved consultant to inspect the work, and the process can take longer than a standard mortgage.
Fannie Mae HomeStyle is similar but not government-insured. It lets you finance renovations up to 50% of the home's after-improved value. HomeStyle requires a 3% to 5% down payment for a purchase, or you can refinance. Both loans require you to work with approved contractors and follow strict draw schedules. They also require a contingency reserve (usually 10% to 20% of the renovation budget) to cover unexpected costs. These loans are powerful for major projects, but they come with more paperwork and timelines that can stretch to 60 days or more for closing.
Before applying, gather bids from licensed contractors and make sure your contractor is willing to work with the loan requirements. Some contractors are not familiar with 203(k) or HomeStyle draw processes and may decline. You can use a service like FreeQuotes.Contractors to request quotes from local professionals; just be sure to ask if they have experience with renovation loans. The extra effort is worth it if you need to finance a large project without draining your savings.
Warnings About Contractor-Arranged Financing and Unlicensed Lenders
When you are eager to start your renovation, a contractor offering to arrange financing on the spot can seem convenient. Be cautious. Contractor-arranged financing often comes through third-party lenders with high fees, inflated interest rates, or hidden prepayment penalties. In some cases, the contractor may steer you toward a lender that pays them a commission, which means you might not get the best deal. Worse, if the contractor goes bankrupt or disappears, you are still on the hook for the loan, even if the work is incomplete. Always compare any contractor-offered financing with at least two independent lenders before signing.
Another red flag is unlicensed lenders. Unlicensed lenders may operate online or through door-to-door solicitation, promising fast cash with no credit check. They often charge exorbitant fees and may use predatory tactics. Before you borrow from any lender, verify their license through your state's financial regulator or the Nationwide Multistate Licensing System (NMLS). Legitimate lenders will provide disclosures and never pressure you to sign immediately. If a deal sounds too good to be true, it probably is. Protect yourself by sticking with well-known banks, credit unions, or online lenders with a proven track record.
Finally, never sign a contract that includes a blank space for the interest rate or that allows the contractor to choose the lender without your approval. Your financing should be in your control, not the contractor's. If you feel pressured, walk away. A reputable contractor will respect your need to compare options.
Steps to Choose the Right Financing for Your Renovation
Now that you understand the main options and pitfalls, here is a practical framework to make your decision. Start by defining the scope and budget of your project. Get at least three contractor bids so you know the real cost range. Then assess your equity: if you have more than 20% equity, a cash-out refinance or HELOC may be attractive. If your project is small (under $50,000) and you have good credit, a personal loan might be the fastest route. For major structural work, explore FHA 203(k) or HomeStyle loans.
Next, evaluate your risk tolerance and timeline. Variable-rate HELOCs carry the risk of rising payments, so if you are on a tight budget, a fixed-rate personal loan or cash-out refinance may be safer. Consider how long you plan to stay in the home; if you are moving within five years, the closing costs of a refinance may not be worth it. Also factor in the draw schedule and paperwork burden. Renovation loans require more time and documentation, so plan accordingly.
Here is a step-by-step checklist to guide you:
- Get at least three contractor bids and a detailed scope of work.
- Check your home equity and credit score.
- Compare rates and fees from at least two lenders for each option you are considering.
- Ask about draw schedules, lien waiver requirements, and prepayment penalties.
- Verify the lender's license and read all disclosures carefully.
Once you have chosen a lender, get preapproved before you sign a contract with a contractor. This gives you negotiating power and ensures you do not face financing surprises mid-project. Keep a contingency fund of 10% to 20% of the project cost in cash for unexpected issues. And remember that financing a renovation is a financial commitment; only borrow what you can comfortably repay.
By taking the time to compare options and understand the fine print, you can finance your renovation without jeopardizing your financial health. Whether you choose a cash-out refinance, a HELOC, a personal loan, or a government-backed renovation loan, the key is to match the financing to your project and your risk profile. With the right preparation, you can turn your renovation dreams into reality.