Contractor License and Insurance Verification Guide
Use this contractor license and insurance verification guide to confirm credentials before hiring. Call (833)-700-4293 for vetted local pros.
By Maya Bennett
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
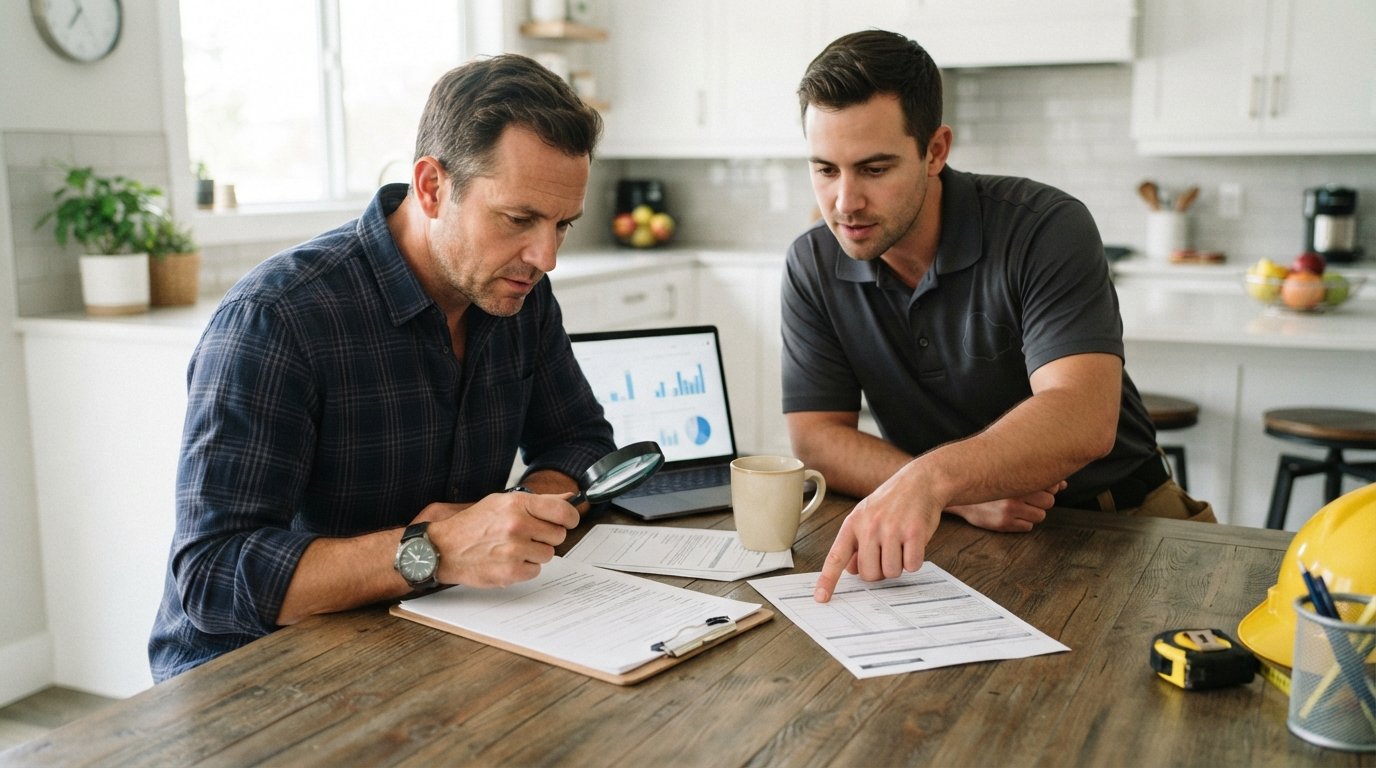
Hiring a contractor is one of the largest financial commitments most homeowners make outside of buying their house. Yet the single most important step, verifying that the contractor is properly licensed and insured, is often skipped in the rush to get a project started. An unlicensed or uninsured worker can leave you holding the bill for injuries, property damage, or substandard work that fails inspection. This contractor license and insurance verification guide walks you through a practical, repeatable process for checking credentials before you sign anything or hand over a deposit. Whether you are planning a roof replacement, a bathroom remodel, or a solar installation, the same core checks apply, and they take less than an hour to complete.
Why Verification Matters More Than Ever
State licensing boards exist to protect homeowners, but enforcement is largely complaint-driven. A contractor can operate without a license for months before anyone notices, and by then the damage is done. Insurance is even trickier: a contractor may carry a policy one month and let it lapse the next, while the certificate you were shown at signing still looks valid. The burden of verification falls squarely on you, the homeowner.
The financial stakes are real. If an uninsured worker is injured on your property, your homeowners insurance may be expected to cover medical bills, and in some states you could face liability beyond your policy limits. If a contractor causes structural damage and has no general liability coverage, your own insurer may deny the claim or raise your rates. Verifying licenses and insurance before work begins is the cheapest form of risk management available to you.
Pre-vetted contractor networks reduce this risk significantly. Platforms like FreeQuotes.Contractors connect homeowners with local professionals who have already had their licenses and insurance reviewed, which means you start the hiring process with a shorter list of qualified candidates. Still, even with a vetted network, a final round of independent verification is a smart habit. This contractor license and insurance verification guide gives you the exact steps.
Step 1: Look Up State and Local License Records
Contractor licensing rules vary widely by state and sometimes by municipality. Some states license general contractors at the state level, others delegate to counties or cities, and a few have no statewide licensing at all for certain trades. The first task is figuring out which authority governs your contractor's trade and location.
Start with your state's licensing board website. Search for terms like "contractor license lookup" plus your state name. Most boards offer an online database where you can search by name, license number, or business name. You will want to confirm four things: that the license is active, that it covers the type of work you are hiring for, that the name on the license matches the business you are dealing with, and that there are no disciplinary actions on record. A license that is expired or listed under a different business name is a red flag.
For local requirements, check your city or county building department website. Many municipalities require separate registration or permits for trades like electrical, plumbing, and HVAC. If your project requires a building permit, the permit application itself will often verify that the contractor is licensed to pull permits in that jurisdiction. Be cautious of any contractor who suggests skipping the permit process, as this usually indicates they cannot legally pull one.
Here is a quick checklist for the license lookup stage:
- Confirm the license status is active and current.
- Verify the license classification matches your project type.
- Match the license name to the business entity and the person you are speaking with.
- Review any complaint or disciplinary history posted by the board.
- Check local registration requirements for your city or county.
Document what you find. Take screenshots or save the search results with the date. If a dispute arises later, having a record of the license status at the time of hiring protects you.
Step 2: Understand General Liability vs. Workers' Compensation
Homeowners often hear "fully insured" and assume that covers everything. In reality, two distinct types of coverage matter for a home improvement project, and they protect different parties.
General liability insurance covers third-party claims for property damage and bodily injury caused by the contractor's operations. If a worker drops a ladder through your window or damages a neighbor's fence, general liability is the policy that responds. It also covers claims from visitors who are injured on your property due to the contractor's work. Most states and licensing boards require general liability coverage, with minimum limits that vary by jurisdiction. A common minimum is $1 million per occurrence, but larger projects may warrant higher limits.
Workers' compensation insurance covers the contractor's employees if they are injured on the job. This is the coverage that protects you from liability when a worker gets hurt on your property. In most states, employers with even one employee are required to carry workers' compensation. If a contractor has no workers' comp policy and a worker is injured, that worker may file a claim against your homeowners policy or sue you directly. The result can be a lengthy legal battle and a significant financial hit. Some states allow sole proprietors with no employees to opt out of workers' comp, but that means the owner themselves is uninsured, which is a risk you should weigh carefully.
When you request proof of insurance, ask for both certificates. A contractor who carries general liability but not workers' comp may be legitimate if they truly have no employees, but you need to confirm that in writing. If they have a crew, workers' comp is non-negotiable.
Step 3: Request and Read a Certificate of Insurance
A certificate of insurance, often called a COI or ACORD form, is a one-page summary issued by the contractor's insurance agent. It lists the policyholder, the insurer, the policy numbers, coverage types, limits, and effective dates. Requesting a COI is standard practice, and any legitimate contractor should provide one without hesitation.
When you receive the COI, read it carefully rather than glancing at the coverage types. Check that the policyholder name matches the contractor's legal business name exactly. Verify that the effective dates cover your entire project timeline, not just the start date. Confirm that the general liability limits meet or exceed what your state requires and what your project warrants. Look for the workers' compensation section and confirm it is active if the contractor has employees.
One important nuance: a COI is not the policy itself. It is a summary, and it can be outdated or even altered. For high-value projects, you can ask the contractor to have their insurer add you as an additional insured on the general liability policy for the duration of the project. This gives you direct rights under the policy if a claim arises. Not every contractor will agree, but it is a reasonable request for large jobs.
You should also verify the COI directly with the insurance agent or carrier. The certificate should list the agent's contact information. A quick call to confirm the policy is active and the limits are accurate takes minutes and closes the loop on potential fraud. If the contractor resists providing a COI or pressures you to skip this step, treat that as a serious warning sign.
Step 4: Know What Happens When an Uninsured Worker Is Injured
The scenario is more common than most homeowners realize. A worker falls from a ladder, cuts a hand on a saw, or suffers a back injury while lifting materials. If the contractor has workers' compensation coverage, the claim goes through that policy, and you are generally protected. If the contractor does not have coverage, the injured worker may look to your homeowners insurance for medical payments or file a lawsuit against you as the property owner.
Homeowners policies often include a small medical payments provision that covers minor injuries to guests regardless of fault, but this is not designed for contractor injuries and may not apply. More concerning, your liability coverage could be triggered if the worker alleges negligence on your part, such as failing to disclose a hazard or hiring an uninsured contractor. Even if your insurer ultimately covers the claim, you may face higher premiums, a deductible, and the stress of a legal process.
Some states have laws that shift liability to the homeowner in certain circumstances, particularly when the homeowner knew or should have known that the contractor was uninsured. This is why documenting your verification efforts matters. If you can show that you requested and reviewed a valid COI, you are in a much stronger position.
The practical takeaway is simple: never assume the contractor's insurance covers everyone on the job. Ask specifically about workers' compensation, and confirm it in writing. If the contractor is a sole proprietor without employees, ask them to sign a statement confirming that status. This protects both of you.
Step 5: Use Pre-Vetted Networks to Reduce Risk
Verifying licenses and insurance for every contractor you consider can be time-consuming, especially if you are gathering multiple quotes. Pre-vetted contractor networks streamline this by screening professionals before they ever reach your shortlist. Platforms like Contractor.Homes connect homeowners with local contractors who have already had their credentials reviewed, which means you spend less time chasing paperwork and more time comparing project details.
Even within a vetted network, you should still perform your own final checks. Ask for the license number and COI, and take a few minutes to confirm them independently. A reputable contractor will respect your diligence. The combination of a vetted network and your own verification creates a strong layer of protection.
When you request quotes through a platform, be specific about your project and your expectations. Mention that you will be verifying licenses and insurance, and ask for those documents upfront. Contractors who are organized and compliant will have them ready. Those who hesitate are telling you something important.
Red Flags to Watch For During Verification
Certain behaviors should prompt you to walk away, regardless of how good the price looks. Being aware of these red flags can save you from a costly mistake.
- Refusal to provide a license number or certificate of insurance.
- A license that is expired, suspended, or registered to a different business name.
- Insurance documents that list policy limits below your state's minimum requirements.
- Pressure to skip permits or start work immediately before paperwork is complete.
- Requests for large cash deposits or payment in full before work begins.
Any one of these is a reason to pause. A legitimate contractor will understand your concerns and provide the documentation you need. If they become defensive or dismissive, consider that a preview of how they will handle problems during the project.
Building Verification Into Your Hiring Routine
Once you have gone through this contractor license and insurance verification guide a few times, the process becomes second nature. Keep a simple folder, digital or physical, for each contractor you consider. Store the license lookup results, the COI, and any correspondence about insurance. This record is valuable if a dispute arises and it also helps you compare contractors on equal footing.
Remember that verification is not a one-time event. Insurance policies can lapse and licenses can be suspended after you hire someone. For long projects, consider re-checking the COI at the midpoint or before final payment. A quick call to the insurance agent can confirm the policy is still active.
The bottom line is that a few hours of diligence upfront can save you tens of thousands of dollars and months of stress. Licensing and insurance are not bureaucratic formalities; they are the foundation of a safe, successful home improvement project. Use this guide as your checklist, ask questions, and do not let anyone rush you past the verification step. Your home and your finances are worth the effort.